Why Working with a Fiduciary Financial Advisor Makes All the Difference
Not every "financial advisor" is held to the same standard, and most people don't discover that difference until it's already cost them money. Understanding what fiduciary duty actually means — and confirming whether your advisor is bound by it — is one of the most consequential steps in choosing who manages your financial life.
Cooke Wealth Management is an independent, fee-based Registered Investment Adviser based in Irvine, California, serving families throughout Orange County and Southern California under a fiduciary standard.
Why This Distinction Gets Overlooked
Many people assume anyone using the title "financial advisor" is legally required to act in their best interest. That assumption isn't always true, and the gap between what people expect and what the law actually requires can have real financial consequences.
What Fiduciary Duty Actually Means
A Legal Obligation, Not a Marketing Term
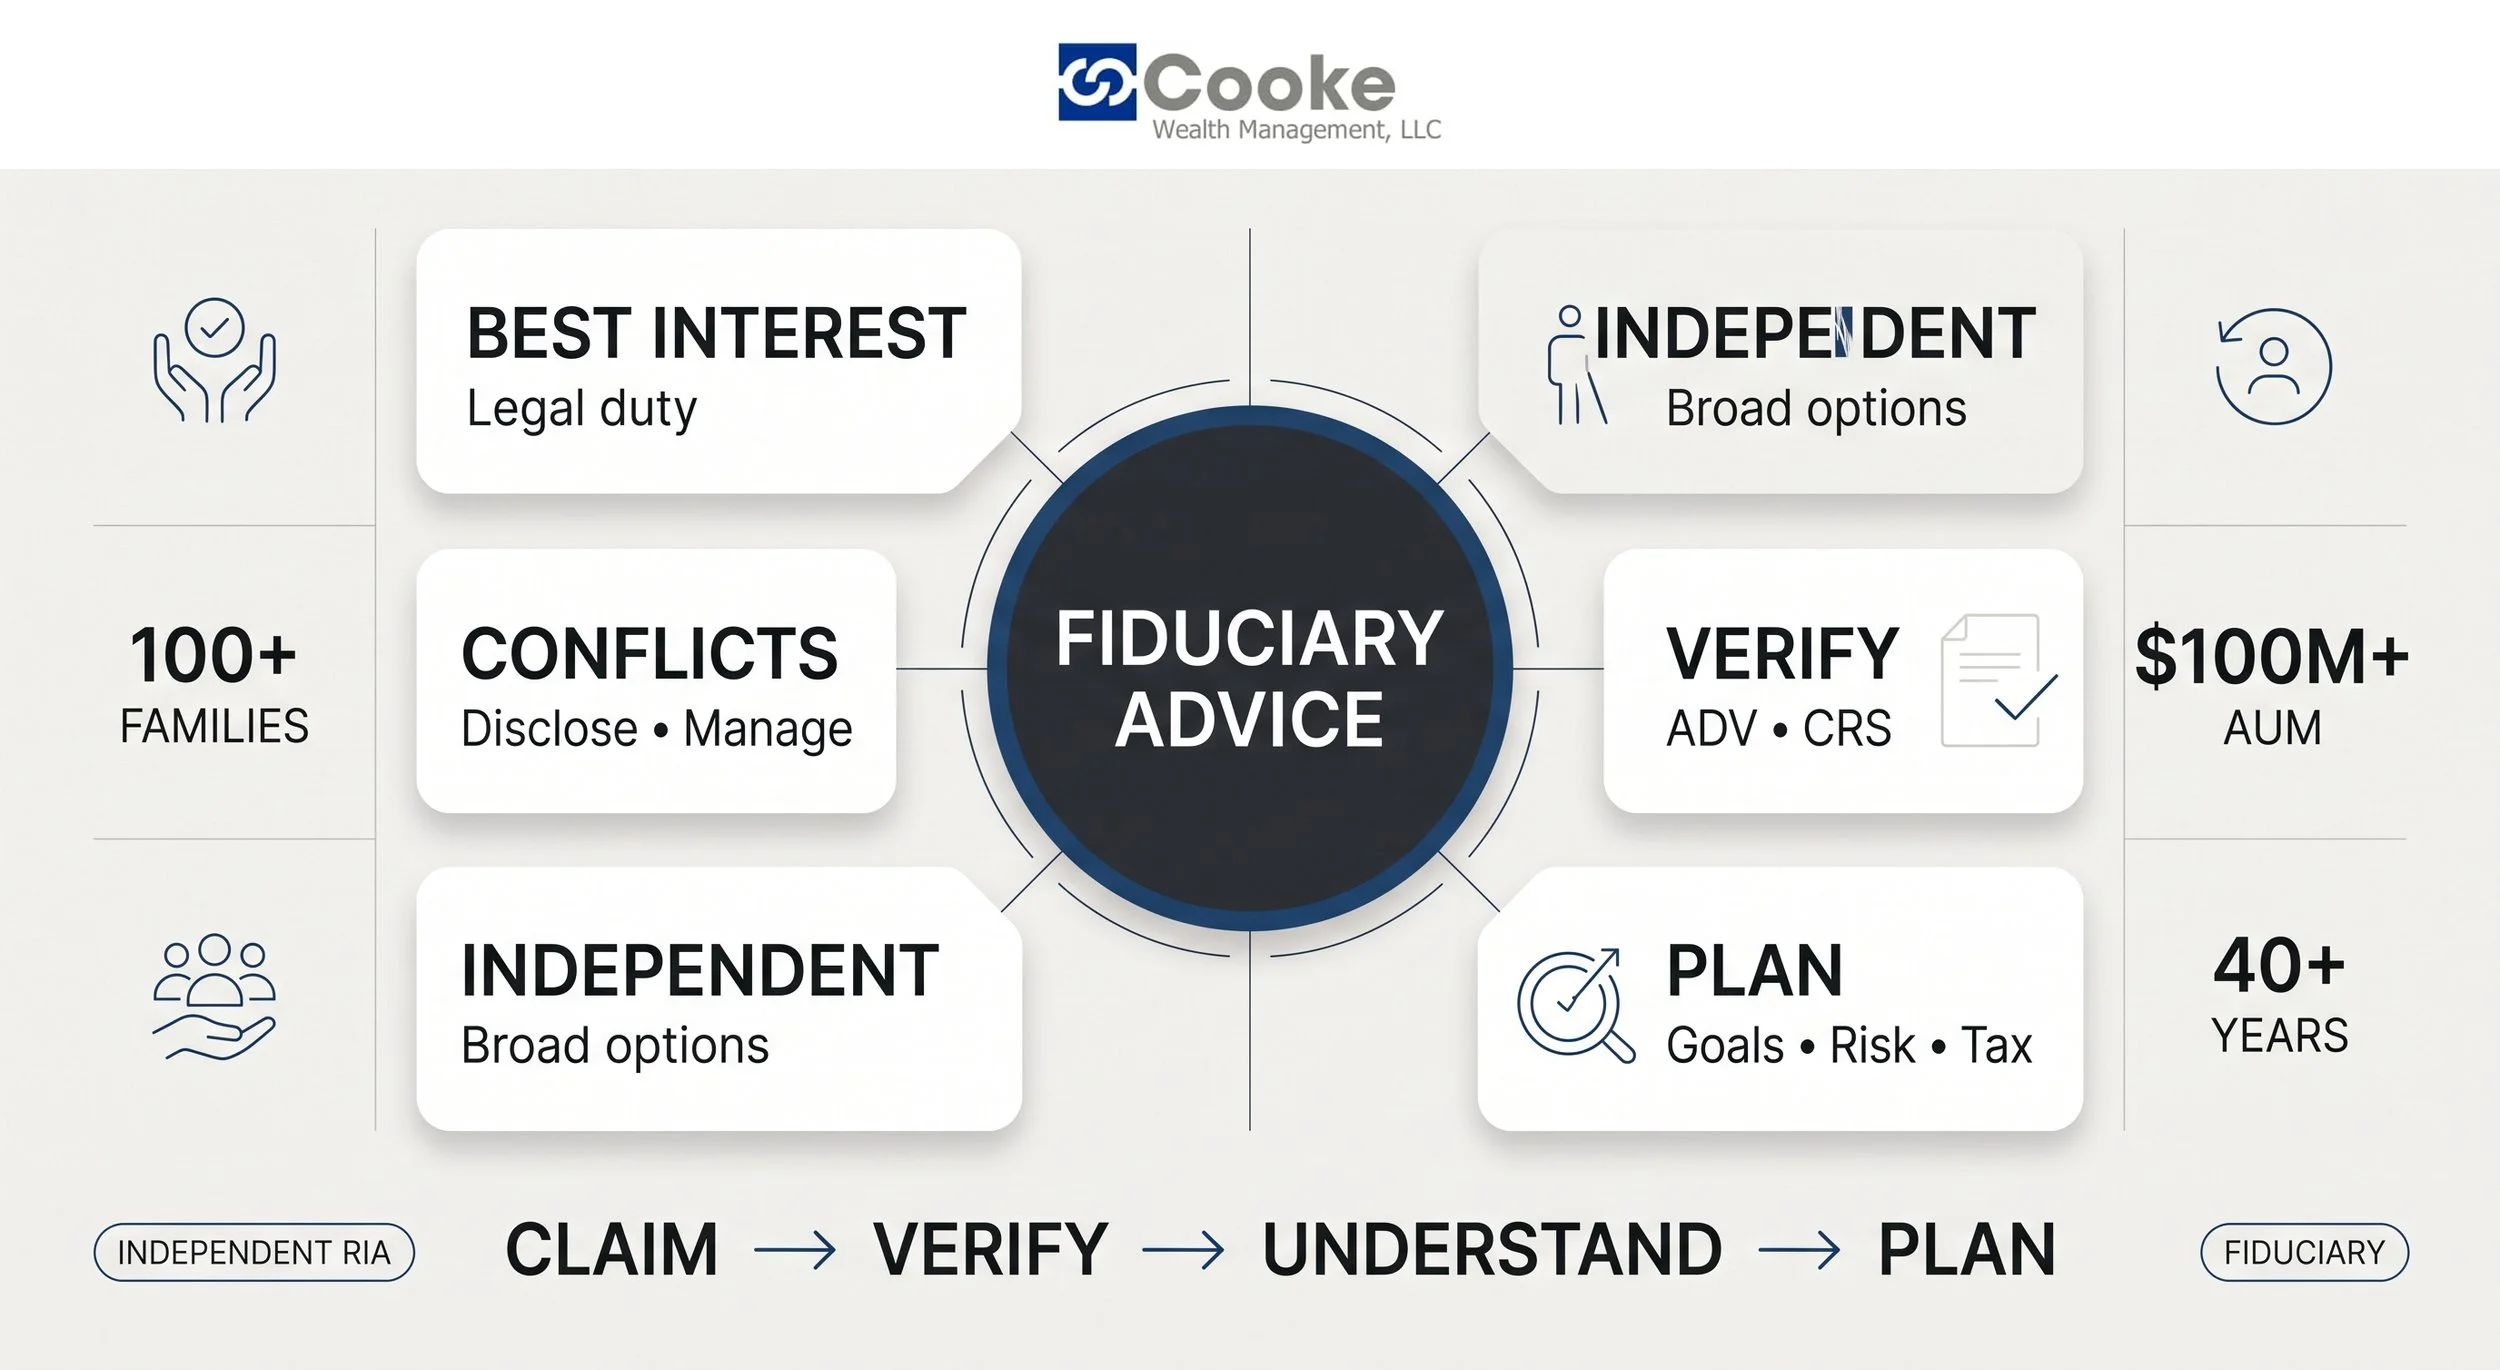
Under the Investment Advisers Act of 1940, Registered Investment Advisers generally owe clients a fiduciary duty, meaning they're legally required to act in the client's best interest across the advisory relationship. This is a higher standard than "suitability," which only requires that a recommendation be appropriate at the moment it's made.
The Practical Difference Between the Two Standards
Under a suitability standard, an advisor can recommend a product that's technically appropriate while still earning a higher commission on it than a comparable alternative would pay. A fiduciary standard is designed to reduce that conflict by tying the advisor's legal obligation directly to your outcome, not their compensation.
A Fiduciary Relationship Doesn't Mean There Are No Conflicts
The SEC's Important Distinction
Being a fiduciary does not mean an advisor is automatically free from conflicts of interest. The SEC's Commission Interpretation on investment adviser fiduciary duty makes clear that the existence of a conflict does not necessarily mean the advisor is prohibited from providing the advice — instead, the duty of loyalty requires the advisor to eliminate the conflict or make full and fair disclosure of it.
Where These Conflicts Come From
Those conflicts can arise from several sources: financial incentives connected to particular investments, compensation from third parties, proprietary product recommendations, affiliated businesses, or other relationships that could influence advice. The SEC's guidance on disclosure of financial conflicts emphasizes that investors should understand the nature and scope of these conflicts, rather than assuming fiduciary status makes them disappear.
A Better Question to Ask
That makes the better question when evaluating a fiduciary advisor not simply "are you a fiduciary?" but "what conflicts exist in your business, and how are they identified and addressed?" Reviewing an advisor's Form ADV and Form CRS can provide additional detail about fees, compensation arrangements, affiliations, and disclosed conflicts.
Transparency Is What Makes Fiduciary Advice Meaningful
A fiduciary relationship therefore provides an important legal framework, but it isn't a guarantee of conflict-free advice. Transparency about conflicts — and how they're managed — is an essential part of what makes fiduciary advice meaningful in practice, not just on paper.
Fiduciary Duty vs. Independence: Two Different Protections
What Independence Adds
Fiduciary duty addresses the legal standard an advisor is held to, while independence addresses whether that advisor is tied to a parent company's proprietary products. An independent, fee-only firm isn't built around promoting one company's investment lineup, which removes another potential source of bias.
Why Both Matter Together
Cooke Wealth Management operates as an independent Registered Investment Adviser, combining both protections: a legal obligation to act in the client's best interest, and a structure that isn't built around selling a specific product line. Clients get the benefit of recommendations drawn from a broad universe of options rather than a limited menu.
How to Verify That an Advisor Is Actually a Fiduciary
Claims Aren't Proof — Disclosures Are
Calling oneself a fiduciary isn't enough — the claim can be verified through regulatory disclosures. Start with the SEC's Investment Adviser Public Disclosure database, which provides public information about registered advisers, including their Form ADV filings.
What Form ADV and Form CRS Reveal
Form ADV Part 1 covers a firm's business, ownership, and control structure, while Part 2 details services, fees, and conflicts of interest. Form CRS, or the Relationship Summary, offers a shorter, standardized comparison tool covering services, fees, conflicts, and disciplinary history in plain language.
Questions Worth Asking Directly
Beyond reviewing disclosures, a few direct questions help clarify how an advisor actually operates: Are you a fiduciary 100% of the time, or only in certain situations? How exactly are you compensated? What conflicts exist in your business, and how are they addressed?
What Fiduciary Guidance Looks Like in Practice
Recommendations Built Around Your Goals
In practice, fiduciary duty means recommendations are built around a client's specific goals, tax situation, and risk tolerance rather than a product an advisor needs to sell. Cooke Wealth Management's investment management process reflects this — portfolios are constructed to align with each client's circumstances rather than a standard model.
Comprehensive Planning, Not Isolated Transactions
Because fiduciary duty applies across the advisory relationship, not just at a single transaction, this obligation naturally extends to comprehensive planning. Cooke Wealth Management's financial planning approach coordinates retirement income, tax strategy, insurance, and wealth transfer, since a fiduciary's obligation covers the full scope of the relationship rather than one recommendation at a time.
Fiduciary Duty and Risk Management
Risk Management Is Part of the Obligation
A fiduciary's responsibility extends to how risk is managed within a client's plan, not just which specific investments are recommended. The SEC notes that every investment involves some degree of risk, and a fiduciary advisor should be building a risk profile around your specific timeline and goals rather than applying a one-size-fits-all approach.
Addressing Concentration and Other Overlooked Risks
Concentration risk — too much wealth tied to a single stock, employer, or property — is a common issue that a fiduciary advisor should proactively address. FINRA warns that concentration can amplify losses, which is exactly the kind of issue a fiduciary relationship should surface rather than leave unmentioned.
Common Misconceptions About Fiduciary Duty
"Fiduciary" Doesn't Mean Guaranteed Performance or Zero Conflicts
Fiduciary duty is about the advisor's legal obligation and conduct, not a guarantee of investment returns or the absence of conflicts. All investments carry risk regardless of who manages them, and every advisor has some form of compensation that creates potential incentives worth understanding.
Not Every Advisor Is a Fiduciary at All Times
Some professionals are fiduciaries only in certain contexts, such as when providing specific advisory services, while operating under a different standard elsewhere in the same relationship. Asking directly whether an advisor is a fiduciary "100% of the time" is a more precise question than asking whether they're a fiduciary at all.
Why Families Choose Cooke Wealth Management
A Track Record Built on Long-Term Relationships
Cooke Wealth Management has served more than 100 families and manages over $100 million in assets, with advisors bringing more than 40 years of combined industry experience. The firm's stated goal is to help clients avoid costly mistakes and build genuine confidence in their financial future.
An Independent Fiduciary Structure
As an independent Registered Investment Adviser, Cooke Wealth Management operates under a fiduciary standard rather than a narrower, commission-driven model. That structure is designed to align the firm's obligations directly with each client's outcomes, not a product line.
Choose an Advisor Whose Obligations Match Your Expectations
The difference between a fiduciary and non-fiduciary advisor isn't just a technicality — it determines whose interests get prioritized when a recommendation is made, and how openly conflicts get disclosed along the way. Verifying that standard before committing to a relationship is worth the extra diligence, given how long these relationships typically last.
Cooke Wealth Management works with individuals and families throughout Orange County and Southern California as an independent, fiduciary Registered Investment Adviser. If you're ready to talk through your goals, scheduling a Discovery Session is a straightforward way to see whether the fit is right.
Frequently Asked Questions
What makes an advisor a fiduciary?
A fiduciary is legally required to act in a client's best interest, a standard that generally applies to Registered Investment Advisers under the Investment Advisers Act of 1940. This differs from a suitability standard, which only requires a recommendation to be appropriate at the time it's made. Confirming an advisor's fiduciary status is one of the most important steps before hiring them.
Does being a fiduciary mean an advisor has no conflicts of interest?
No. The SEC's guidance makes clear that fiduciary duty requires an advisor to identify and either eliminate or fully disclose conflicts, not that conflicts don't exist in the first place. Nearly every advisor has some form of compensation that could create a potential incentive. What matters is whether those conflicts are disclosed and appropriately managed.
How can I verify that an advisor is actually a fiduciary?
You can review an advisor's Form ADV through the SEC's Investment Adviser Public Disclosure database, along with their Form CRS, which offers a shorter, standardized summary of services and conflicts. It's also reasonable to ask directly whether the advisor is a fiduciary 100% of the time or only in certain circumstances.
Is a fee-only advisor the same as a fiduciary advisor?
Not necessarily, though the two often overlap. Fee-only refers to how an advisor is compensated, while fiduciary refers to a legal standard of care. It's worth confirming both independently rather than assuming one implies the other.
Does working with a fiduciary guarantee better investment returns?
No. Fiduciary duty concerns the advisor's legal obligation and conduct, not a guarantee of specific outcomes, and all investments carry some degree of risk regardless of who manages them. What a fiduciary standard does provide is legal accountability for how conflicts of interest are handled.
What are common sources of conflicts of interest for financial advisors?
Commissions, asset-based compensation, revenue sharing, and incentives tied to proprietary products are all recognized sources of potential conflicts. Not every conflict means an advisor is acting improperly, but understanding how an advisor is paid helps clarify where those incentives might point.
How do I get started with Cooke Wealth Management?
Cooke Wealth Management offers a free Discovery Session to discuss your financial goals and determine whether the firm's independent, fiduciary approach fits your needs. From there, the firm builds a personalized plan rather than applying a generic template. You can schedule that initial conversation directly through the firm's contact page.