Costa Mesa Wealth Management: Your Partner in Building Lasting Financial Security
Building lasting financial security in Costa Mesa often means juggling career income, a growing family, and a long list of "someday" goals that never quite get a dedicated plan. Finding a wealth management partner who treats those goals as connected, rather than a stack of separate to-dos, tends to make the difference over time.
Cooke Wealth Management is an independent, fee-based wealth management firm based in nearby Irvine, serving families throughout Costa Mesa, Orange County, and Southern California. The firm's approach centers on coordinated financial planning rather than isolated investment advice.
Why "Lasting" Security Requires More Than a Portfolio
A strong investment return in a given year doesn't automatically translate into long-term financial security. Security comes from a plan that holds up across market cycles, career changes, and family transitions — which requires more coordination than picking good investments alone.
What Wealth Management Actually Includes
The Core Areas of a Coordinated Plan
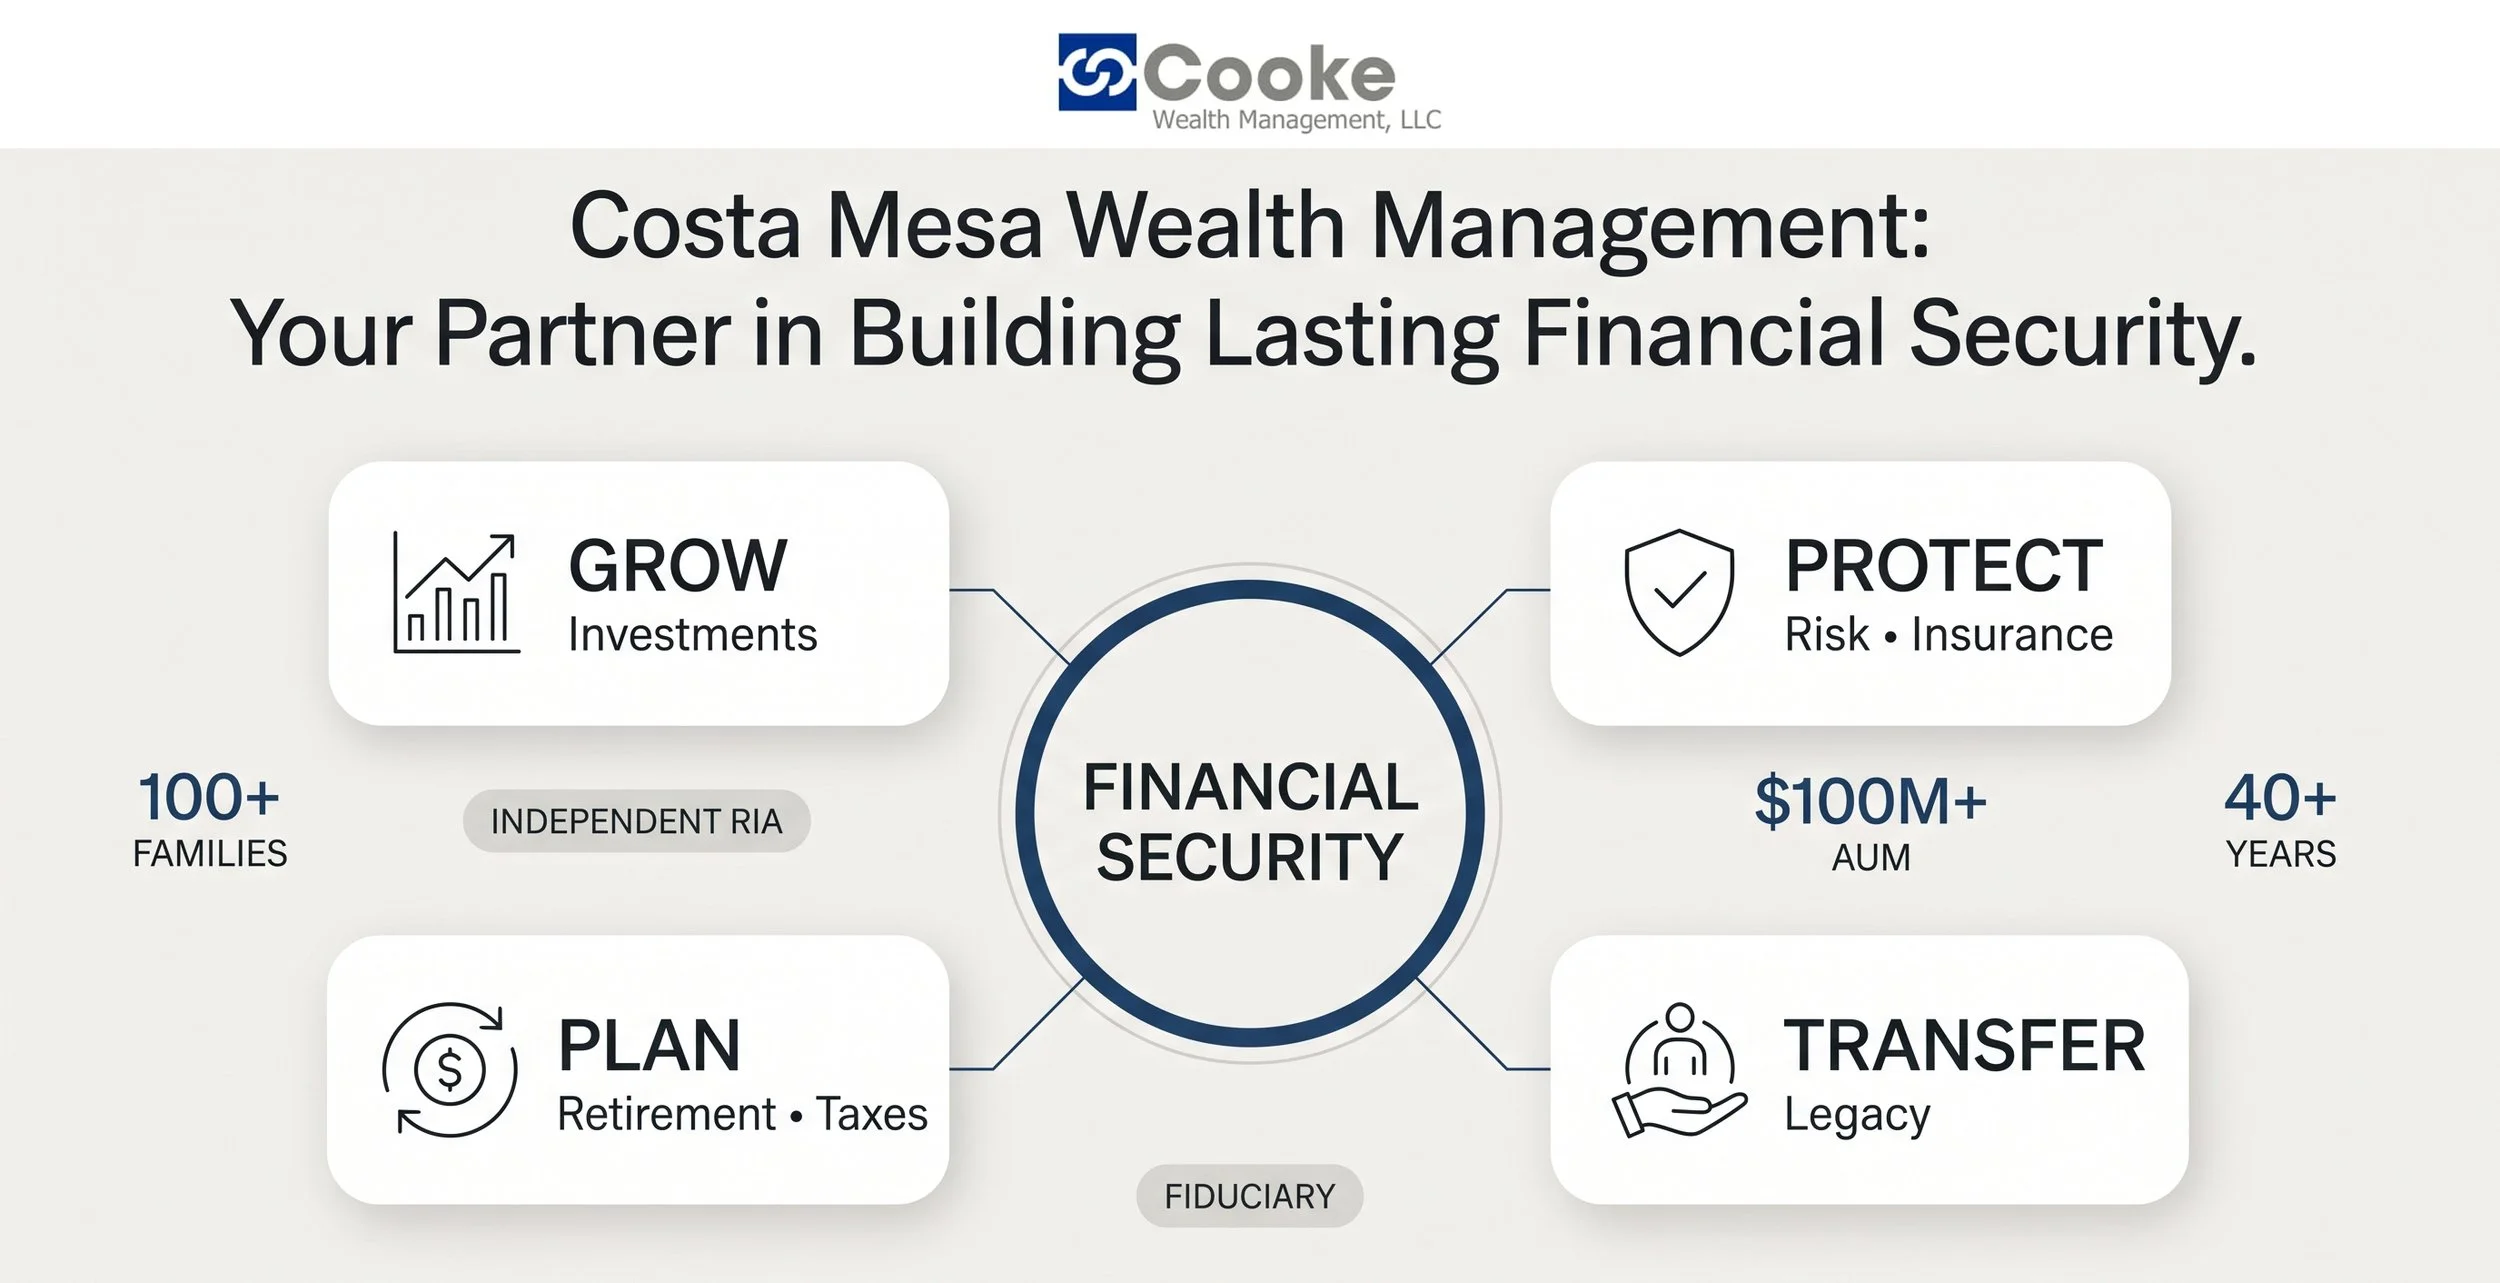
Wealth management typically covers retirement income planning, tax-aware investment strategy, insurance review, and wealth transfer guidance, evaluated together rather than in isolation. A decision in one area — say, a Roth conversion — routinely affects taxes, retirement income, and even estate planning at the same time.
How Cooke Wealth Management Structures This Work
Cooke Wealth Management organizes its work around financial planning, investment management, retirement planning, and wealth transfer strategy. The firm builds a personalized plan for each client, then works with them on an ongoing basis to implement and adjust it as circumstances change.
Why Costa Mesa Clients Have Specific Planning Needs
A Mix of Careers and Business Owners
Costa Mesa's economy includes a mix of corporate professionals, small business owners, and families connected to the area's retail, hospitality, and creative industries. Each of these situations introduces its own planning considerations — equity compensation, business cash flow, or freelance income — that a generic retirement calculator doesn't capture well.
Real Estate as Part of the Picture
Home equity often represents a significant share of net worth for Costa Mesa homeowners, given the area's property values. Decisions about home equity, downsizing, or purchasing investment property typically need to be coordinated with the rest of a client's financial plan rather than treated as standalone transactions.
The Fiduciary Standard and Why It Matters
What Fiduciary Duty Actually Requires
Under the Investment Advisers Act of 1940, Registered Investment Advisers generally owe clients a fiduciary duty, meaning they must act in the client's best interest rather than simply recommend a "suitable" product. That obligation applies across the ongoing advisory relationship, not just at the point of a single transaction.
Independence Reduces Certain Conflicts
An independent, fee-only firm isn't tied to a parent company's proprietary product lineup, which reduces the incentive to steer clients toward in-house investments. Cooke Wealth Management operates as an independent Registered Investment Adviser, drawing recommendations from a broad universe of options rather than a limited menu.
What Financial Security Actually Means
A Risk-Management System, Not a Balance
Financial security is more than having a large investment balance or choosing a conservative portfolio. It's better understood as a risk-management system designed to protect your ability to meet financial goals when circumstances change. The SEC notes that appropriate asset allocation depends on both your investment time horizon and risk tolerance, while diversification can reduce the impact of any single investment performing poorly.
Liquidity, Market, and Inflation Risk
That framework should extend beyond market performance. Liquidity risk asks whether you have enough accessible cash to handle an unexpected expense without selling long-term investments at an unfavorable time. Market risk addresses the possibility that declining asset values could disrupt your goals, and inflation risk considers whether your assets and income will maintain their purchasing power as costs rise — FINRA specifically notes that even relatively conservative investments can face inflation risk.
Longevity, Tax, and Concentration Risk
Longevity risk is the possibility of outliving your assets, making retirement income planning particularly important. Tax risk involves the potential consequences of poorly coordinated withdrawals, investment sales, or changes in tax circumstances. Concentration risk arises when too much wealth depends on one stock, employer, asset class, or property, and FINRA warns that this can amplify losses even when a portfolio contains multiple investments.
Insurance and Income Risk
There are also insurance and income risks: inadequate coverage can leave a household exposed to a major financial loss, while an unexpected job or business-income interruption can undermine otherwise sound plans. These risks live outside the investment portfolio entirely but affect financial security just as much.
Why Coordination, Not Elimination, Is the Goal
The goal, therefore, isn't to eliminate every risk. It's to identify which risks could derail your specific goals and build safeguards around them. A genuinely secure wealth plan coordinates investments, cash reserves, insurance, taxes, income, and long-term objectives rather than treating each risk separately.
How the Financial Planning Process Works
Starting With a Complete Financial Picture
Effective planning starts with a full view of income, expenses, investments, insurance, taxes, and long-term goals. Skipping this step is one of the most common reasons plans fail to hold up — recommendations built on incomplete information tend to break down the first time circumstances change.
An Ongoing Relationship, Not a Static Document
From there, a personalized plan gets built around a client's specific goals and revisited as life evolves. Cooke Wealth Management frames this as an ongoing relationship: clients work with their advisor to implement the plan, then adjust it over time rather than receiving a document that sits untouched for years.
Events That Typically Call for a Plan Update
Certain life events tend to require a fresh look at an existing plan, including:
A job change, promotion, or new business venture
Marriage, divorce, or the birth of a child
Buying or selling a home in Costa Mesa's market
An inheritance or unexpected windfall
Retirement approaching within the next five to ten years
Choosing a Wealth Management Firm in Costa Mesa
Questions Worth Asking Before You Commit
A few direct questions can reveal how a firm actually operates: Are you a fiduciary at all times, or only in certain situations? How are you compensated, and do you receive commissions on any products? What does your typical client's situation look like, and does mine fit that profile?
Why Local Familiarity Still Matters
An advisor familiar with Costa Mesa and the broader Orange County market brings context that matters — local real estate dynamics, California-specific tax considerations, and access to in-person meetings when useful. That local grounding, paired with a genuinely coordinated planning process, often distinguishes a firm worth hiring from one that simply has a nearby office.
Why Families Choose Cooke Wealth Management
A Track Record Built on Long-Term Relationships
Cooke Wealth Management has served more than 100 families and manages over $100 million in assets, with advisors bringing more than 40 years of combined industry experience. The firm's stated goal is to help clients avoid costly mistakes and build genuine confidence in their financial future.
A Values-Informed, Fiduciary Structure
The firm also incorporates biblical principles and academic research into its planning process, which resonates with some Orange County families specifically. Paired with its structure as an independent Registered Investment Adviser, that approach gives clients a planning relationship built around their stated priorities rather than a product to sell.
Start Building Lasting Financial Security
Financial security isn't something you arrive at once and then forget about — it's built and maintained through a plan that adapts as your life does. The right Costa Mesa wealth management partner treats that process as an ongoing relationship, not a single transaction.
Cooke Wealth Management works with individuals and families throughout Costa Mesa, Orange County, and Southern California to build personalized financial plans grounded in fiduciary guidance. If you're ready to talk through your goals, scheduling a Discovery Session is a straightforward way to see whether the fit is right.
Frequently Asked Questions
What does a wealth management firm in Costa Mesa actually do?
A wealth management firm typically coordinates investment management, retirement planning, tax-aware strategy, insurance review, and wealth transfer guidance into a single plan. The goal is to align financial decisions across all these areas rather than treating them as separate, unrelated tasks. Scope varies by firm, so it's worth confirming exactly what's included.
How is an independent wealth management firm different from a bank or brokerage?
An independent firm isn't tied to a parent company's proprietary products, which can reduce certain conflicts of interest when making recommendations. Bank and brokerage advisors may have incentives to recommend in-house funds or products. Confirming an advisor's independence and fiduciary status is a reasonable first step in any evaluation.
How much money do I need to work with a wealth management firm?
Asset minimums vary significantly by firm, and some Orange County-based firms work with clients across a range of net worth levels. Flat-fee or hourly planning arrangements can also be an option for those who don't meet a firm's asset minimum for ongoing investment management. It's worth asking directly rather than assuming you don't qualify.
What is concentration risk, and why should Costa Mesa homeowners care?
Concentration risk is the risk of amplified losses from having too much wealth tied to a single investment, property, or employer. For many Costa Mesa homeowners, home equity represents a large share of net worth, which can create this kind of imbalance without a coordinated plan. Addressing it usually means evaluating diversification alongside real estate and retirement goals together.
What's the difference between financial planning and investment management?
Financial planning covers the full picture — retirement income, taxes, insurance, and estate considerations — while investment management focuses specifically on building and managing a portfolio. Many wealth management firms, including Cooke Wealth Management, offer both as part of a coordinated approach. Some clients want only one service, while others want both combined.
How often should I review my financial plan?
Most advisors recommend at least an annual review, with additional check-ins after major life events like a job change, inheritance, or approaching retirement. A plan that isn't revisited regularly can become outdated as circumstances shift. Ongoing communication is often a better indicator of a strong advisor relationship than short-term performance alone.
How do I get started with Cooke Wealth Management?
Cooke Wealth Management offers a free Discovery Session to discuss your financial goals and determine whether the firm's approach fits your needs. From there, the firm builds a personalized plan rather than applying a generic template. You can schedule that initial conversation directly through the firm's contact page.