Retirement Planning Advisors Laguna Beach: Helping You Retire with Confidence
Retiring with confidence in Laguna Beach means more than reaching a savings number — it means knowing your income will hold up against market swings, rising costs, and a retirement that could last decades. For residents whose wealth is often tied up in coastal real estate, concentrated equity, or a business, that confidence usually requires more coordination than a standard retirement calculator provides.
Cooke Wealth Management is an independent, fiduciary wealth management firm based in nearby Irvine, providing retirement planning for families throughout Laguna Beach, Orange County, and Southern California.
What Does Retirement Confidence Actually Look Like?
A Test, Not Just a Feeling
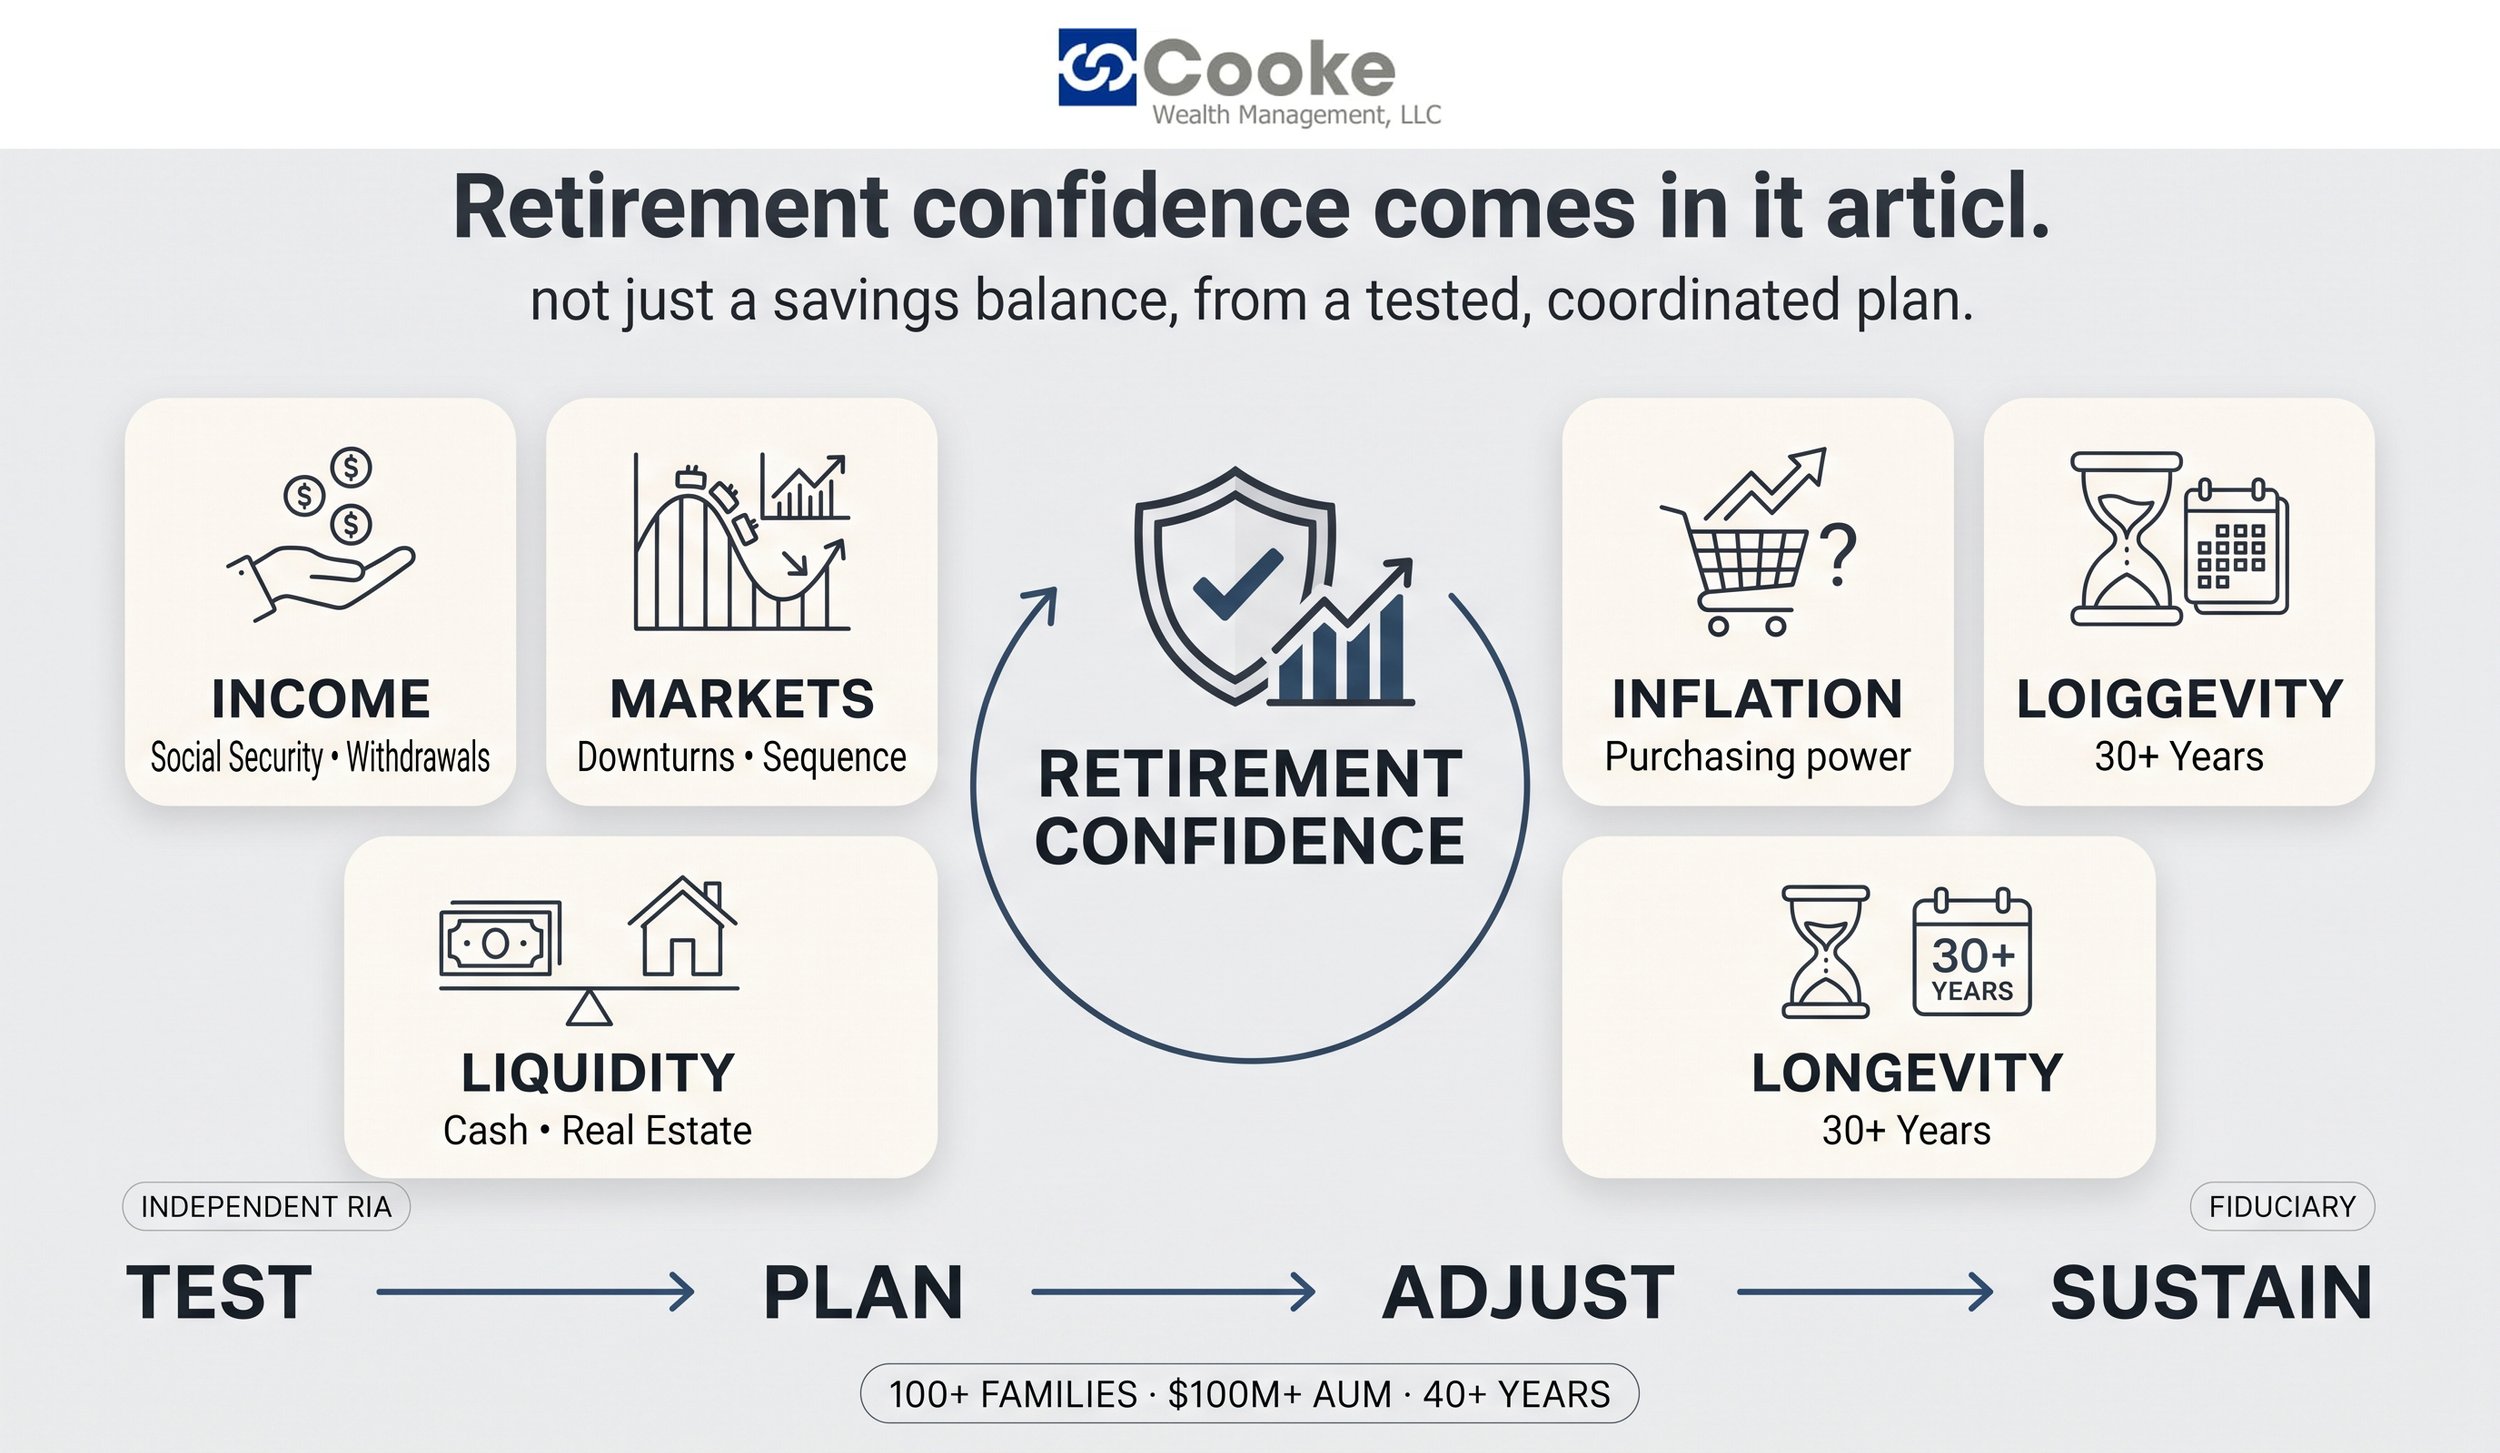
Retirement confidence should be something a financial plan can test, not simply a feeling that comes from seeing a large account balance. A useful confidence test asks whether the plan remains workable when the assumptions surrounding retirement change. This reflects CFP Board's view of financial planning as an integrated process that considers a client's personal and financial circumstances, goals, risks, and alternative courses of action rather than evaluating each decision in isolation.
Eight Questions a Practical Confidence Test Should Ask
A practical retirement confidence test should examine:
Income sufficiency: Can expected income cover essential spending throughout retirement?
Longevity: Does the strategy remain viable if retirement lasts 30 years or longer?
Market resilience: What happens if a significant market decline occurs shortly after retirement?
Inflation: Can income maintain purchasing power as living costs rise?
Liquidity: Are enough readily accessible assets available without forcing an unfavorable sale of investments or property?
Tax exposure: How could withdrawals, required distributions, and other income affect the household's tax liability?
Concentration: Is too much retirement security dependent on a single property, business, employer, or investment?
Flexibility: Which spending or withdrawal decisions can be adjusted if markets, expenses, or personal circumstances change?
Why Monitoring Never Really Stops
The final point is particularly important because retirement planning shouldn't end when the initial plan is implemented. CFP Board's process includes monitoring progress and updating recommendations as circumstances change, rather than treating the plan as a document to file away.
The Real Question Behind "Do I Have Enough?"
For a Laguna Beach retiree, that means confidence should come from knowing not only "do I have enough?" but also "what happens if things don't go according to plan?" A retirement strategy that can withstand different market, inflation, longevity, tax, and spending scenarios provides a far more meaningful measure of preparedness than a single projected account balance.
What Retiring With Confidence Actually Requires
A Coordinated Income Strategy, Not Just a Savings Number
Confidence in retirement comes from knowing specifically how income will be generated year to year — not just from having accumulated a large balance. That requires coordinating Social Security timing, investment withdrawals, and any real estate or business proceeds into a single, sequenced strategy.
Sequencing Withdrawals Across Account Types
Sustainable retirement income typically depends on sequencing withdrawals across taxable, tax-deferred, and tax-free accounts in a way that manages the overall tax burden year to year. Cooke Wealth Management's retirement planning work is built around this kind of sequencing, since the order withdrawals happen in can materially affect how long a portfolio lasts.
Coordinating Social Security Timing
When to claim Social Security is one of the more consequential decisions in a retirement plan, since claiming earlier reduces the monthly benefit while delaying it increases the benefit through delayed retirement credits up to age 70. This decision should be evaluated alongside other income sources and spending needs, not made in isolation.
Sequence-of-Returns Risk: Why Timing Matters More Near Retirement
The Danger of a Downturn Early in Retirement
A market downturn shortly before or after retirement can do more lasting damage than the same downturn a decade earlier, because there's less time to recover before ongoing withdrawals are required. This is known as sequence-of-returns risk, and it's one of the more overlooked threats to a retirement plan.
How Advisors Help Manage This Risk
Common approaches include maintaining a cash reserve to avoid selling investments during a downturn, adjusting withdrawal rates based on market conditions, and diversifying income sources so retirement isn't entirely dependent on portfolio performance in a given year. A financial planner can help determine which combination of these strategies fits a specific retirement timeline.
Concentration Risk and Coastal Real Estate
Why Concentration Deserves Special Attention Here
Concentration risk — too much wealth tied to a single stock, property, or employer — is a common issue for Laguna Beach clients with significant home equity or concentrated equity compensation. FINRA warns that concentration can amplify losses even within an otherwise reasonable-looking financial picture.
Balancing Real Estate Against Liquidity Needs
A retirement plan heavily weighted toward an illiquid property needs a clear strategy for generating accessible income, whether through downsizing, a home equity approach, or drawing more heavily on other assets. Addressing this directly, rather than assuming a home will "figure itself out," is part of what builds genuine retirement confidence.
Inflation and Longevity Over a Multi-Decade Retirement
Why Inflation Erodes Confidence Over Time
Inflation risk, the gradual loss of purchasing power, becomes more consequential the longer a retirement lasts. A retirement income plan built around static, non-adjusting withdrawals can leave a retiree with meaningfully reduced purchasing power a decade or two into retirement.
Planning for a Retirement That Could Last 30 Years
Longevity risk, the possibility of outliving retirement assets, has become more relevant as life expectancies have increased. A sustainable withdrawal strategy needs to account for a retirement that could realistically last three decades, not just the first ten or fifteen years.
The Fiduciary Standard Behind Confident Retirement Planning
A Legal Obligation Across the Relationship
Under the Investment Advisers Act of 1940, Registered Investment Advisers generally owe clients a fiduciary duty, meaning they're legally required to act in the client's best interest across the advisory relationship. This matters particularly for retirement planning, since the relationship typically spans decades rather than a single transaction.
Fiduciary Duty Doesn't Mean Zero Conflicts
Being a fiduciary doesn't mean an advisor has no conflicts of interest — nearly every advisor has some form of compensation that creates potential incentives. What matters is whether those conflicts are identified and disclosed, which can be verified through an advisor's Form ADV on the SEC's Investment Adviser Public Disclosure database.
Independence Reduces Certain Conflicts
An independent, fee-only firm isn't tied to a parent company's proprietary product lineup, which reduces the incentive to steer clients toward in-house investments. Cooke Wealth Management operates as an independent Registered Investment Adviser, drawing recommendations from a broad universe of options rather than a limited menu.
What Comprehensive Retirement Planning Includes
Coordinating Investments, Insurance, and Estate Planning
A comprehensive retirement plan coordinates investment management, insurance review, and wealth transfer guidance rather than addressing each separately. Cooke Wealth Management's investment management work builds portfolios aligned with a client's income needs and risk tolerance, since a retirement portfolio generally requires a different approach than one built purely for accumulation.
An Ongoing Relationship That Adjusts With You
Retirement needs change as circumstances evolve — healthcare costs increase, spending patterns shift, and market conditions vary from year to year. Cooke Wealth Management frames retirement planning as an ongoing relationship, revisiting the plan regularly rather than delivering a single static projection.
Choosing a Retirement Planning Advisor in Laguna Beach
Questions Worth Asking Directly
A few direct questions can reveal how an advisor approaches retirement specifically: How do you sequence withdrawals across different account types? How do you address concentration risk for clients with significant real estate or equity? Are you a fiduciary 100% of the time, and how are you compensated?
Why Local Familiarity Still Matters
An advisor familiar with Laguna Beach brings context that matters — coastal real estate dynamics, California-specific tax considerations, and an understanding of the area's cost of living. That local grounding, paired with genuine retirement expertise, often distinguishes an advisor worth trusting from one who simply has a nearby office.
Why Laguna Beach Residents Choose Cooke Wealth Management
A Track Record Built on Long-Term Relationships
Cooke Wealth Management has served more than 100 families and manages over $100 million in assets, with advisors bringing more than 40 years of combined industry experience. That experience includes working with retirees whose income needs to last across multiple decades and market cycles.
A Fiduciary, Independent Structure
As an independent Registered Investment Adviser, Cooke Wealth Management operates under a fiduciary standard rather than a narrower, commission-driven model. That structure is designed to align the firm's obligations directly with each client's retirement outcomes, not a product to sell.
Retire With a Plan Built for Confidence
Confidence in retirement doesn't come from a single savings target — it comes from a coordinated plan that's been tested against market declines, inflation, longevity, and the specific complexities of your financial picture. For Laguna Beach residents, that often means addressing real estate and concentrated wealth directly, not as an afterthought.
Cooke Wealth Management works with individuals and families throughout Laguna Beach, Orange County, and Southern California to build retirement plans grounded in fiduciary guidance. If you're ready to talk through your retirement goals, scheduling a Discovery Session is a straightforward way to see whether the fit is right.
Frequently Asked Questions
What does it mean to "retire with confidence"?
Retiring with confidence means having a plan that's been tested against scenarios like a market downturn, higher inflation, or a longer-than-expected retirement, rather than simply reaching a savings target. It requires knowing not just "do I have enough" but "what happens if things don't go according to plan." A financial planner can help translate a general sense of readiness into a specific, tested strategy.
How does owning a home in Laguna Beach affect retirement planning?
Home equity often represents a significant share of net worth for Laguna Beach homeowners, which can create both an opportunity and a liquidity challenge in retirement. Decisions about downsizing, selling, or holding the property need to be coordinated with the rest of a retirement income strategy. A generic plan that ignores real estate can miss a major piece of the picture.
What is sequence-of-returns risk, and why does it matter so much near retirement?
Sequence-of-returns risk is the danger that poor investment performance early in retirement, combined with ongoing withdrawals, can permanently damage a portfolio's ability to last. It matters more in the years just before and after retirement than during the accumulation years, since there's less time to recover from a downturn. Strategies like cash reserves and flexible withdrawal rates can help manage this risk.
When should I claim Social Security?
The right claiming age depends on your health, other income sources, and overall retirement income strategy, since claiming earlier reduces the monthly benefit while waiting increases it through delayed retirement credits up to age 70. There's no single correct answer for everyone, which is why this decision should be evaluated alongside the rest of a retirement plan.
What is concentration risk, and why should Laguna Beach retirees care?
Concentration risk is the risk of amplified losses from having too much wealth tied to a single investment, property, or employer. Laguna Beach retirees with significant home equity or concentrated stock positions may be more exposed to this risk than they realize. A coordinated plan evaluates diversification and liquidity together with retirement income needs.
Is a fiduciary retirement advisor automatically free of conflicts of interest?
No. Fiduciary duty requires an advisor to identify and either eliminate or fully disclose conflicts of interest, not to have none at all. Understanding how conflicts are disclosed and managed matters more than assuming a fiduciary label means conflict-free advice.
How do I get started with Cooke Wealth Management?
Cooke Wealth Management offers a free Discovery Session to discuss your retirement goals and determine whether the firm's approach fits your needs. From there, the firm builds a personalized plan rather than applying a generic template. You can schedule that initial conversation directly through the firm's contact page.