Wealth Management Laguna Beach: Your Trusted Fiduciary Advisor
Laguna Beach households often have a financial picture that's more complex than a typical retirement calculator can handle — coastal real estate, concentrated equity from a career or business sale, and a lifestyle that comes with its own cost considerations. Finding a fiduciary advisor who can manage that complexity as one coordinated plan matters more here than in many other markets.
Cooke Wealth Management is an independent, fee-based wealth management firm based in nearby Irvine, serving families throughout Laguna Beach, Orange County, and Southern California. As a Registered Investment Adviser, the firm operates under a fiduciary standard rather than a narrower, commission-driven model.
Why "Trusted" and "Fiduciary" Are Connected
Trust in a financial relationship isn't just a feeling — it can be backed by a legal standard. A fiduciary advisor is required to act in your best interest, which gives "trusted" a concrete meaning beyond how an advisor presents themselves.
What Fiduciary Duty Actually Means
A Legal Standard, Not a Marketing Term
Under the Investment Advisers Act of 1940, Registered Investment Advisers generally owe clients a fiduciary duty, meaning they're legally required to act in the client's best interest across the advisory relationship. This differs from a "suitability" standard, which only requires that a recommendation be appropriate at the moment it's made.
Why the Distinction Matters in Practice
An advisor operating under a narrower standard can recommend a product that's suitable while still earning a higher commission on it than a comparable alternative. A fiduciary standard is meant to reduce that kind of conflict, since the advisor's legal obligation is tied to your outcome, not their compensation.
Why Independence Matters for Laguna Beach Clients
Recommendations From a Broad Universe, Not a Product List
An independent, fee-only firm isn't tied to a parent company's proprietary product lineup. Cooke Wealth Management operates as an independent Registered Investment Adviser, meaning its recommendations are drawn from a wide range of options rather than a limited menu tied to one company's revenue targets.
How This Plays Out With Complex Assets
Independence matters most when a recommendation involves a real tradeoff — a lower-cost fund versus a proprietary one, for instance. For Laguna Beach clients with concentrated equity positions or coastal real estate holdings, that independence supports recommendations built around the client's actual situation rather than a product a firm needs to move.
A Laguna Beach Wealth Planning Checklist
Why a Household-Level View Matters Here
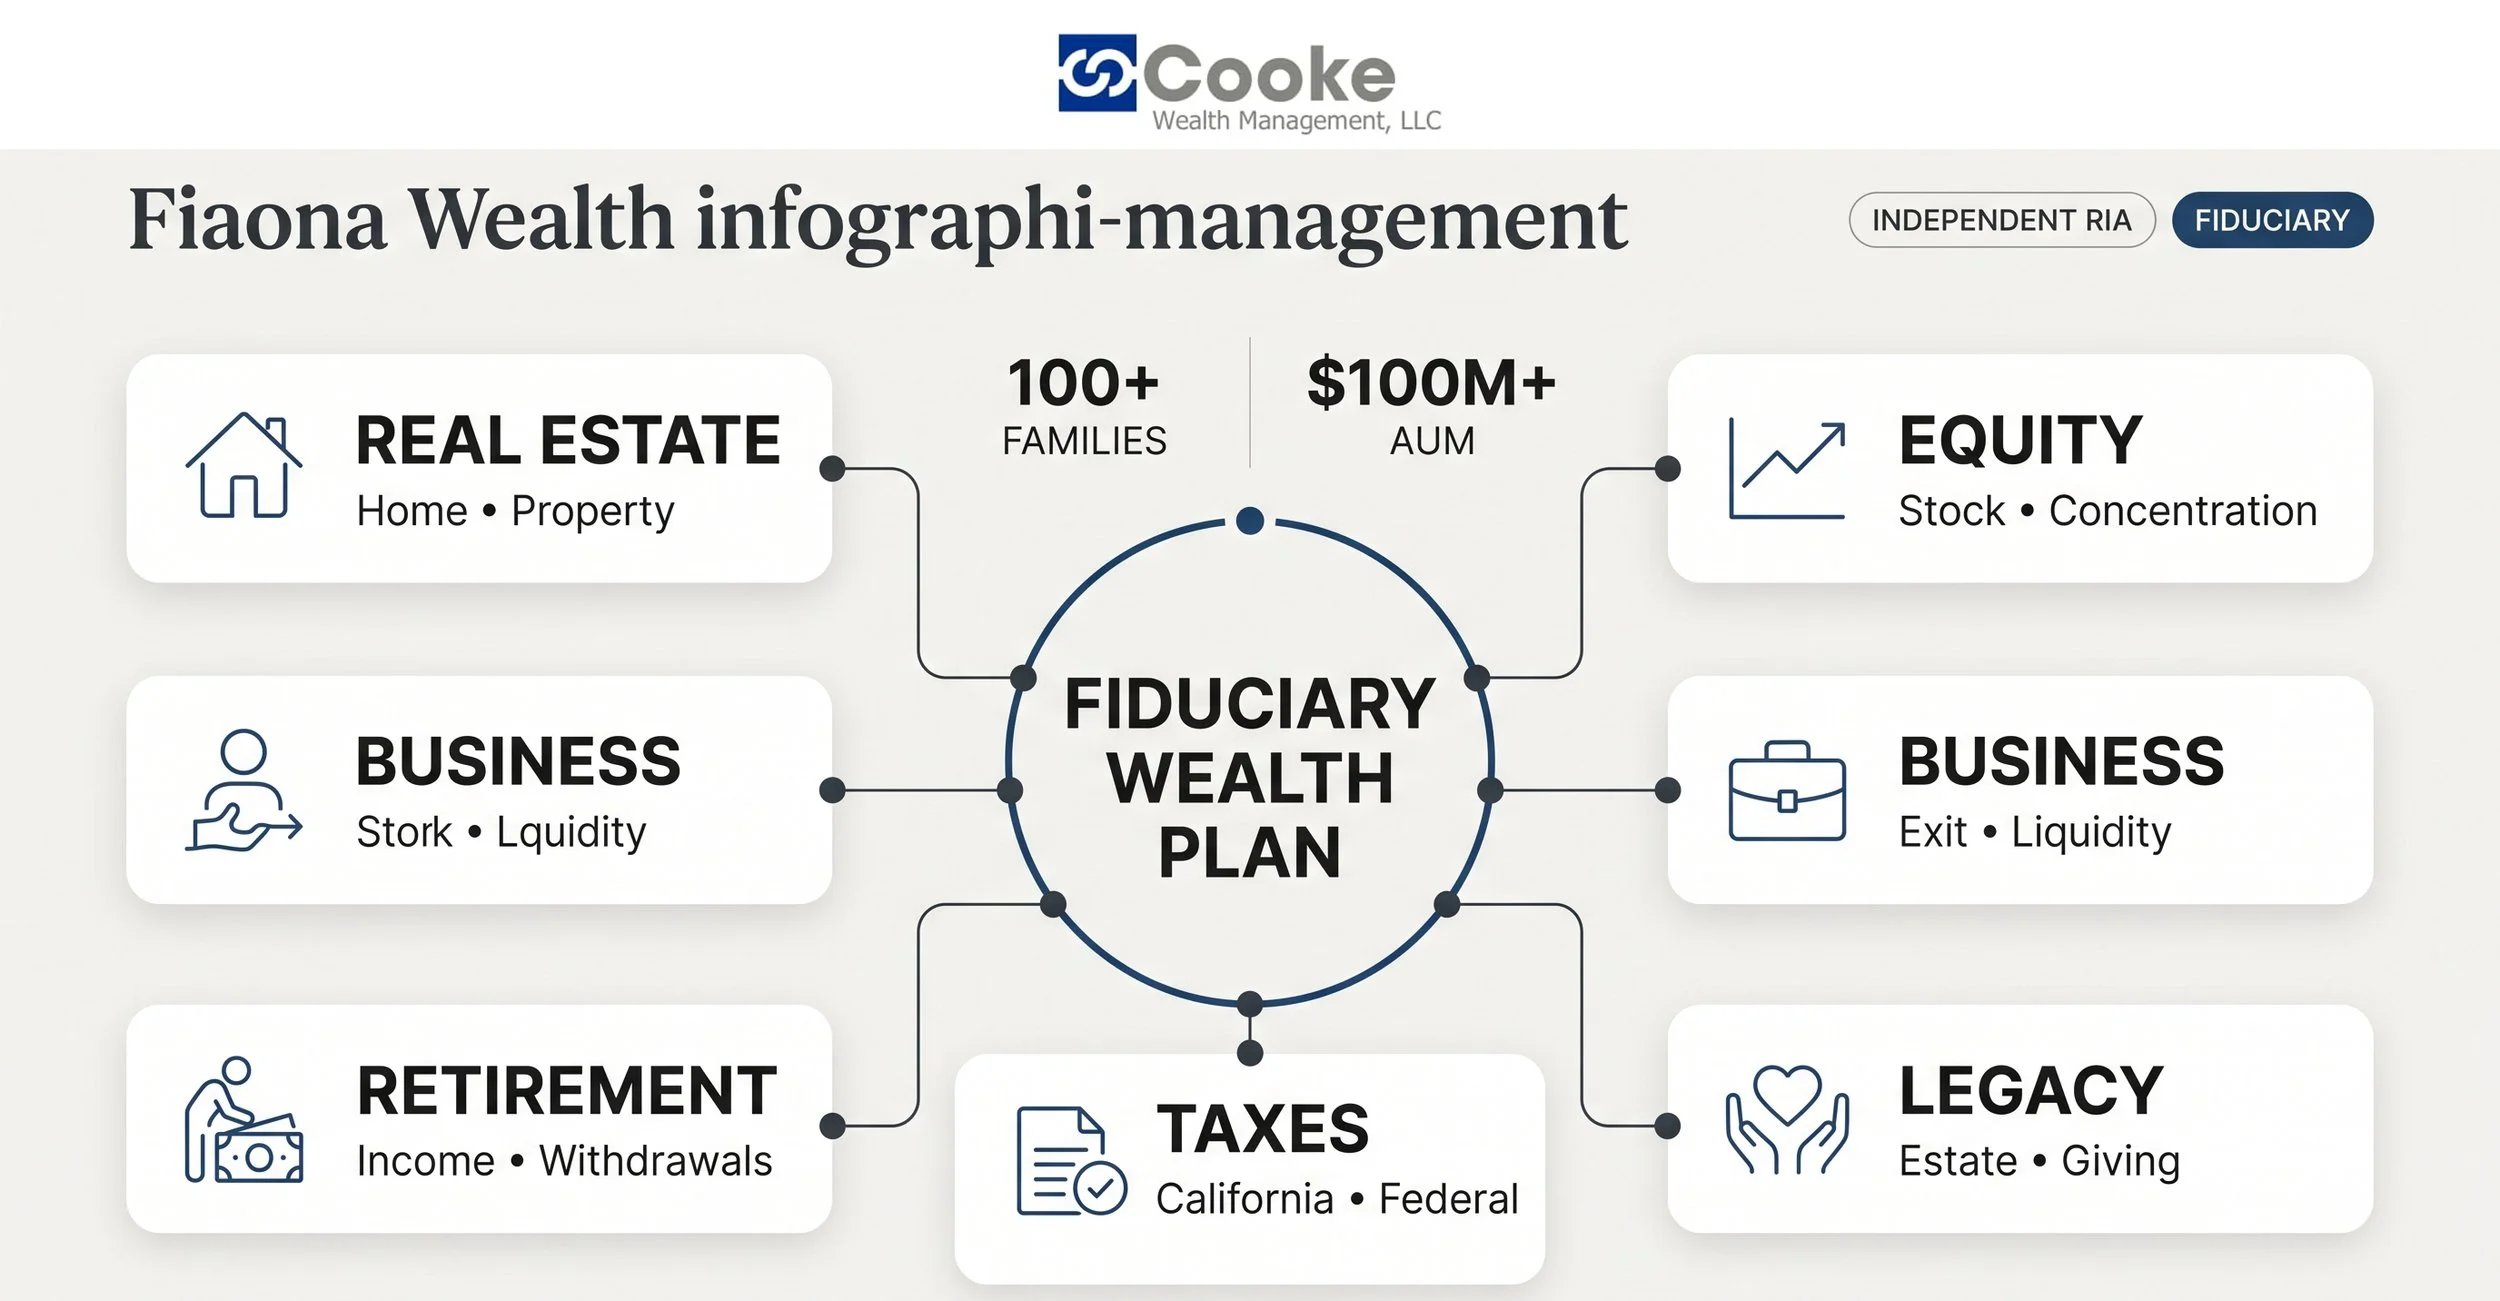
For Laguna Beach households, wealth management may require looking beyond an investment portfolio to understand how real estate, business interests, taxes, and future income fit together. A useful starting point is a household-level checklist that touches every major piece of the balance sheet.
Primary Residence
Review home equity, adjusted tax basis, liquidity, and how the property fits into the overall balance sheet. The IRS notes that a property's basis is important when determining gain or loss on a future sale, which matters given how much coastal property values have appreciated.
Second or Vacation Property
Evaluate whether holding, selling, or restructuring the property aligns with cash-flow needs, investment objectives, and tax considerations. A second property that made sense five years ago may no longer fit the rest of the plan as goals shift.
Concentrated Stock
Review cost basis, diversification, and potential tax consequences before reducing a large position. FINRA warns that concentration in a single investment can amplify losses, which is a common issue for clients with significant equity compensation.
Business Ownership
Consider succession, potential exit timing, and how a future liquidity event would affect the rest of the financial plan. Business owners often underestimate how much a sale or transition will ripple into taxes, retirement timing, and estate planning all at once.
Retirement
Map expected income sources against spending needs and investment withdrawals rather than viewing retirement as a single portfolio target. A number on a statement means little without a plan for how it translates into sustainable income.
Taxes
Evaluate both federal and California exposure. California, for example, does not provide a separate lower capital-gains rate — capital gains are generally taxed as ordinary income at the state level, which can significantly change the math on a large sale.
Estate and Legacy
Review trusts, beneficiaries, wealth-transfer objectives, and charitable goals. These documents tend to go stale faster than people expect, especially after a major life event or a significant change in asset values.
Insurance
Consider property, liability, life, and long-term-care coverage as part of broader risk management. Coastal real estate in particular can carry unique property and liability exposures worth reviewing regularly.
Liquidity
Compare readily accessible reserves with wealth tied up in real estate, businesses, or other illiquid assets. FINRA identifies liquidity as a distinct investment risk, and it's an especially relevant one in a market where a large share of net worth can sit in property.
The Goal Is Coordination, Not a Checklist
The goal isn't simply to check every box, but to understand how each decision affects the others. A financial planner's real value often shows up in these connections — how a business sale affects tax planning, or how a real estate decision affects retirement timing — rather than in any single line item.
What Comprehensive Wealth Management Includes
The Core Building Blocks of a Coordinated Plan
A comprehensive plan typically covers retirement income planning, tax-aware investment strategy, insurance review, and wealth transfer guidance, evaluated together since a decision in one area often affects the others. Cooke Wealth Management's investment management work focuses on building portfolios aligned with a client's specific goals and risk tolerance rather than applying a generic model.
An Ongoing Relationship, Not a One-Time Document
The firm builds a personalized plan for each client, then works with them on an ongoing basis to implement and adjust it as circumstances change. That ongoing structure matters more for Laguna Beach clients whose financial pictures — real estate values, equity positions, business interests — tend to shift meaningfully over time.
How to Evaluate a Fiduciary Advisor in Laguna Beach
Questions That Reveal How an Advisor Actually Works
A few direct questions can clarify how a firm operates: Are you a fiduciary 100% of the time, or only in certain situations? How are you compensated, and do you receive commissions on any recommended products? What does your typical client's financial situation look like?
Confirming Fiduciary Status Independently
Beyond asking directly, it's worth reviewing an advisor's Form ADV through the SEC's Investment Adviser Public Disclosure database to confirm registration status, fee structure, and any disclosed conflicts of interest. This step provides independent verification rather than relying solely on what an advisor states in conversation.
Why Local Familiarity Still Counts
An advisor familiar with Laguna Beach and the broader Orange County market brings context that matters — coastal real estate dynamics, California-specific tax considerations, and local knowledge that a remote generalist firm may not have. That familiarity, paired with a genuinely fiduciary structure, often distinguishes a trusted advisor from one who simply has a nearby office.
Why Families Choose Cooke Wealth Management
A Track Record Built on Long-Term Relationships
Cooke Wealth Management has served more than 100 families and manages over $100 million in assets, with advisors bringing more than 40 years of combined industry experience. The firm's stated goal is to help clients avoid costly mistakes and build genuine confidence in their financial future, rather than simply managing a portfolio.
A Values-Informed Approach Behind the Fiduciary Structure
The firm also incorporates biblical principles and academic research into its planning process, which resonates with some Orange County clients specifically. Combined with its structure as an independent Registered Investment Adviser, that approach gives clients a planning relationship built around their stated priorities rather than a product to sell.
Find a Fiduciary Advisor You Can Actually Trust
Trust in a financial relationship should be backed by more than good intentions — it should be backed by a legal standard that requires an advisor to act in your best interest. That's what a genuine fiduciary relationship offers, and it's worth confirming before committing to any advisor.
Cooke Wealth Management works with individuals and families throughout Laguna Beach, Orange County, and Southern California who want a wealth management relationship built on fiduciary guidance. If you're ready to talk through your goals, scheduling a Discovery Session is a straightforward way to see whether the fit is right.
Frequently Asked Questions
What makes an advisor a fiduciary?
A fiduciary is legally required to act in a client's best interest, a standard that generally applies to Registered Investment Advisers under the Investment Advisers Act of 1940. This differs from a suitability standard, which only requires a recommendation to be appropriate at the time it's made. Confirming an advisor's fiduciary status is one of the most important steps before hiring them.
How do I verify that an advisor is actually a fiduciary?
You can review an advisor's Form ADV through the SEC's Investment Adviser Public Disclosure database, which discloses registration status, fees, and any conflicts of interest. It's also reasonable to ask the advisor directly whether they're a fiduciary at all times or only in certain situations. Both steps together provide a more complete picture than either alone.
Why do Laguna Beach clients often need more specialized wealth management?
Laguna Beach households frequently hold significant wealth in coastal real estate or concentrated equity positions, which require more coordination than a standard financial plan. Decisions involving property sales, stock options, or business transitions usually intersect with taxes and investment strategy at the same time. A generalist plan can miss those interactions.
Is a fee-only advisor the same as a fiduciary advisor?
Not necessarily, though the two often overlap. Fee-only refers to how an advisor is compensated, while fiduciary refers to a legal standard of care. It's possible, though less common, for an advisor to be one without fully being the other, so it's worth confirming both independently.
How does California tax capital gains differently than the federal government?
California does not offer a preferential rate for long-term capital gains the way the federal government does. Instead, capital gains are taxed as ordinary income at California's regular income tax rates, which can significantly affect the total tax owed on a large sale. This is an important consideration for anyone planning to sell concentrated stock, a business, or appreciated real estate.
What is concentration risk, and why does it matter for Laguna Beach real estate owners?
Concentration risk is the risk of amplified losses from having too much wealth tied to a single investment, property, or employer. Laguna Beach homeowners with significant equity in a single property may be more exposed to this risk than they realize. A coordinated plan can help evaluate whether diversification adjustments are appropriate given your overall financial picture.
How do I get started with Cooke Wealth Management?
Cooke Wealth Management offers a free Discovery Session to discuss your financial goals and determine whether the firm's fiduciary approach fits your needs. From there, the firm builds a personalized plan rather than applying a generic template. You can schedule that initial conversation directly through the firm's contact page.