Wealth Management in Huntington Beach: Tailored Strategies for Your Future

Huntington Beach households span a wide range of financial situations — young families building savings, business owners navigating a sale, and retirees converting decades of coastal real estate appreciation into income. A one-size-fits-all financial plan rarely serves any of these situations well, which is why wealth management here needs to start with the specific person, not a generic template.
Cooke Wealth Management is an independent, fee-based Registered Investment Adviser based in nearby Irvine, providing financial planning and investment management for families throughout Huntington Beach, Orange County, and Southern California.
Why "Tailored" Matters More Than It Sounds
Generic Plans Miss the Details That Matter Most
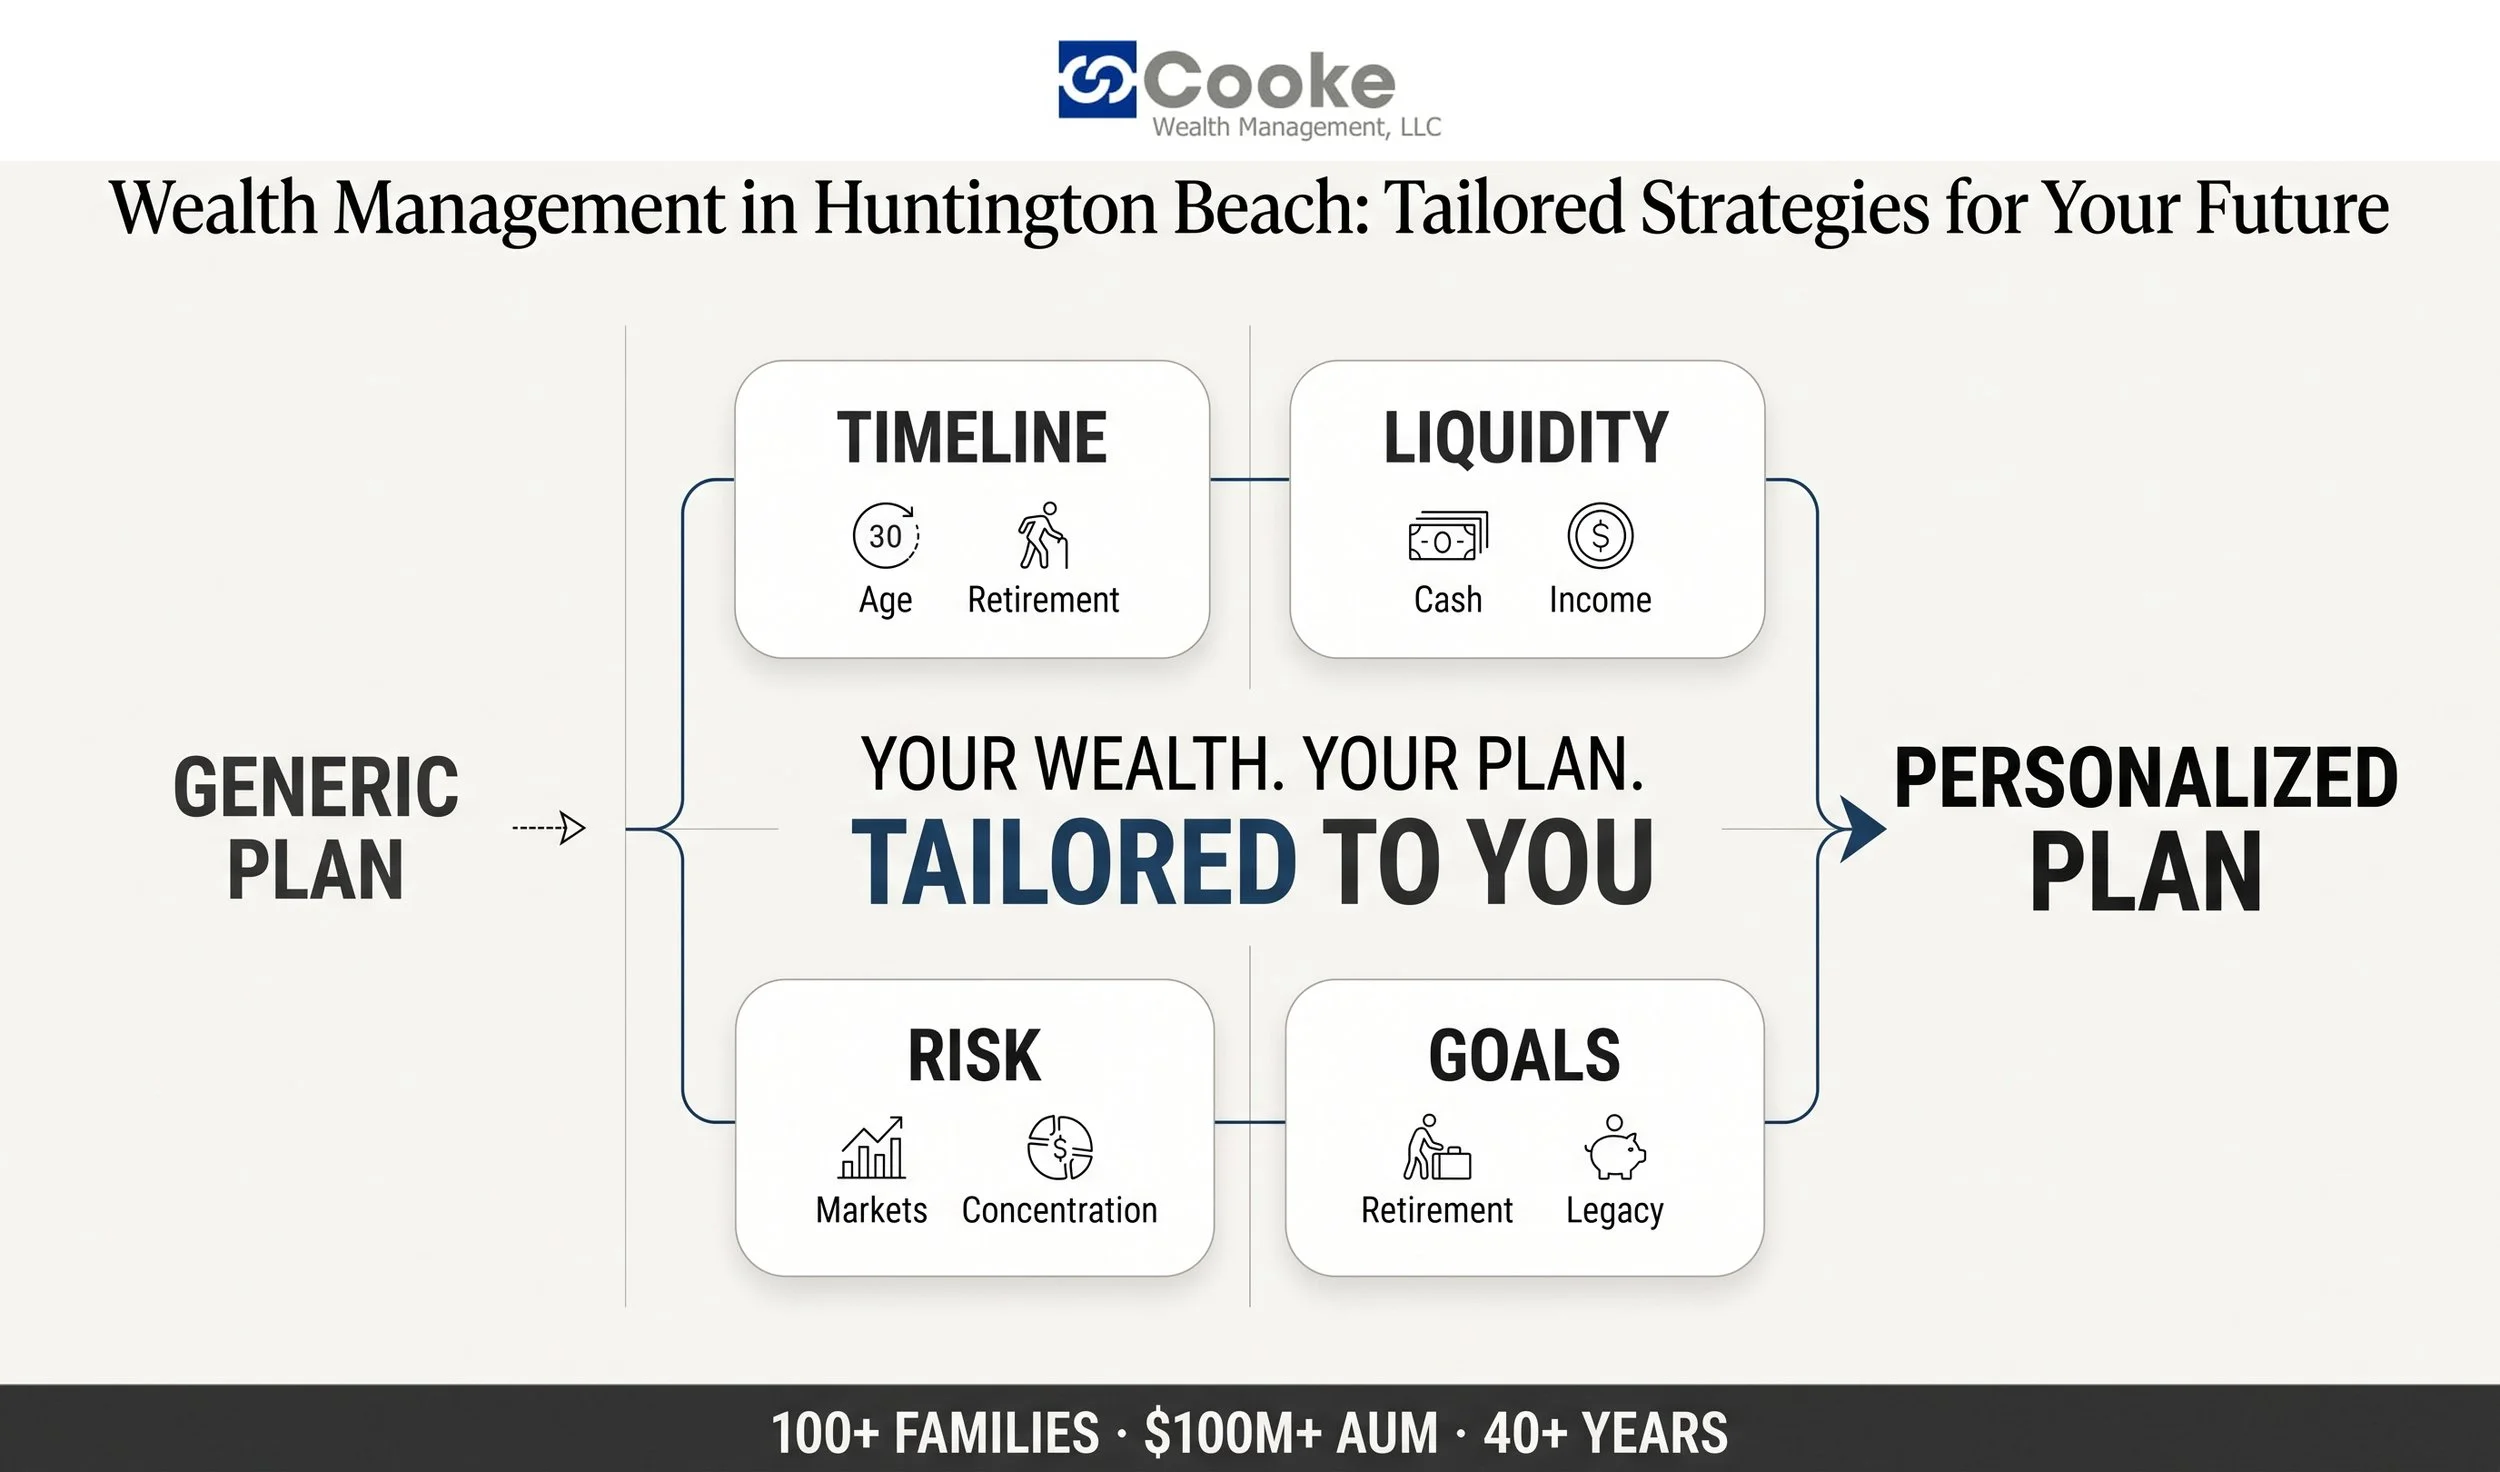
A retirement calculator built around national averages, or a portfolio model applied the same way to every client, tends to miss the specific details that actually drive good financial decisions — a concentrated stock position, a business sale timeline, or a coastal property that represents a large share of net worth. Tailored planning starts by understanding those specifics before making any recommendations.
What Tailoring Looks Like in Practice
In practice, tailoring means a plan built around your actual income, tax situation, risk tolerance, and goals, rather than a template applied uniformly. It also means revisiting the plan as your circumstances change, since a strategy that fit five years ago may no longer fit today.
Build a Tailored Plan Stress Test
Two Similar Portfolios Can Need Very Different Strategies
A financial strategy that works well for one Huntington Beach household may be inappropriate for another — even when their portfolios look similar on paper. The difference often comes down to when the money will be needed, how much liquidity the family requires, and what the assets are ultimately intended to accomplish.
Two Hypothetical Families With the Same $2 Million
Consider two hypothetical families with $2 million invested. A 35-year-old couple with stable income and retirement decades away may have a much longer investment horizon than a 65-year-old couple already drawing portfolio income. The SEC notes that asset allocation should reflect an investor's time horizon and risk tolerance, and that those factors can change throughout life.
Six Questions a Proper Stress Test Should Ask
| Factor | Question to test |
|---|---|
| Age & timeline | When will these assets actually be needed? |
| Income | Can employment income cover current expenses? |
| Liquidity | How much cash may be needed unexpectedly? |
| Risk tolerance | How much market loss can the family withstand? |
| Goals | Is the money for retirement, education, legacy, or another purpose? |
| Concentration | How much wealth is already tied to the home, employer, or business? |
CFP Board similarly emphasizes evaluating a client's goals, income, expenses, assets, liabilities, liquidity, taxes, and risk capacity together rather than in isolation. The point isn't to find one universally "correct" portfolio — it's to test whether the strategy still makes sense for this family, at this stage of life, pursuing these specific goals.
Building a Tailored Financial Plan
Starting With a Complete Financial Picture
Effective planning starts with a full view of income, expenses, investments, insurance, taxes, and long-term goals. Skipping this step is one of the most common reasons financial plans fail to hold up — recommendations built on incomplete information tend to break down the first time circumstances change.
A Personalized Plan, Not a Template
Cooke Wealth Management's financial planning process builds a plan around your specific circumstances, then works with you on an ongoing basis to implement and adjust it. This matters especially for Huntington Beach clients whose financial pictures — real estate values, business interests, career changes — tend to shift meaningfully over time.
Investment and Retirement Strategies Built Around You
Time Horizon and Risk Tolerance Drive Allocation
Cooke Wealth Management's investment management approach builds portfolios aligned with each client's specific timeline and risk tolerance, reflecting the same logic behind the stress test above — a 35-year-old and a 65-year-old with identical balances often need very different strategies. Diversification and cost-awareness both matter here, since even small ongoing fees can meaningfully reduce portfolio value over time.
Why Huntington Beach's Cost of Living Changes the Retirement Math
Huntington Beach's cost of living, particularly housing, changes what "enough" looks like for retirement compared to national averages. Cooke Wealth Management's retirement planning work focuses on sequencing withdrawals across taxable, tax-deferred, and tax-free accounts, since the order withdrawals happen in can materially affect how long a portfolio lasts.
Real Estate and Concentrated Wealth: Common Huntington Beach Realities
Home Equity as a Significant Share of Net Worth
Many Huntington Beach homeowners hold a substantial share of net worth in a single coastal property, given the area's real estate values. A useful starting point is calculating home equity as a percentage of total net worth — the higher that percentage, the more the rest of the plan should account for that concentration.
Concentration Risk From Equity Compensation
Concentration risk — too much wealth tied to a single stock, property, or employer — is also common among Huntington Beach professionals with significant equity compensation. FINRA warns that concentration can amplify losses, which makes diversification a specific area a tailored plan should address directly.
The Fiduciary Standard Behind a Tailored Strategy
A Legal Obligation, Not Zero Conflicts
Under the Investment Advisers Act of 1940, Registered Investment Advisers generally owe clients a fiduciary duty, meaning they're legally required to act in the client's best interest. Being a fiduciary doesn't mean an advisor has no conflicts of interest — nearly every advisor has some form of compensation that creates potential incentives. What matters is whether those conflicts are identified and disclosed, which can be verified through an advisor's Form ADV on the SEC's Investment Adviser Public Disclosure database.
Independence Supports Genuinely Tailored Recommendations
Cooke Wealth Management operates as an independent Registered Investment Adviser, meaning it isn't built around promoting a parent company's proprietary product lineup. That independence supports recommendations drawn from a broad universe of options, which is part of what makes a strategy genuinely tailored rather than limited to a preset menu.
Milestones That Call for Revisiting Your Plan
Life Events That Typically Require an Update
Certain life events tend to require a fresh look at an existing plan, including:
A career change, promotion, or business transition
Marriage, divorce, or the birth of a child
Buying or selling a home in Huntington Beach's market
An inheritance or unexpected windfall
Retirement approaching within the next five to ten years
A plan built five years ago around a specific set of circumstances may no longer reflect your current income, goals, or risk tolerance — revisiting it regularly is part of what keeps a tailored strategy tailored.
Choosing a Wealth Management Firm in Huntington Beach
Questions Worth Asking Directly
A few direct questions can reveal how a firm actually tailors its approach: How do you build a plan around my specific situation rather than a template? Are you a fiduciary at all times, and how are you compensated? How do you address concentration risk if a large share of my wealth is tied to my home or employer stock?
Why Local Familiarity Still Matters
An advisor familiar with Huntington Beach brings context that matters — local real estate dynamics, California-specific tax considerations, and an understanding of the area's cost of living. That local grounding, paired with genuinely individualized planning, often distinguishes a firm worth hiring from one that simply has a nearby office.
Why Huntington Beach Families Choose Cooke Wealth Management
A Track Record Built on Long-Term Relationships
Cooke Wealth Management has served more than 100 families and manages over $100 million in assets, with advisors bringing more than 40 years of combined industry experience. The firm's stated goal is to help clients avoid costly mistakes and build genuine confidence in their financial future.
A Values-Informed, Fiduciary Structure
The firm also incorporates biblical principles and academic research into its planning process, which resonates with some Orange County families specifically. Paired with its structure as an independent Registered Investment Adviser, that approach gives clients a planning relationship built around their stated priorities rather than a product to sell.
Build a Strategy Tailored to Your Future
A tailored wealth management strategy starts with understanding your specific situation — not applying a generic model and hoping it fits. Running your own version of the stress test above, and asking whether your current strategy still matches your timeline, liquidity needs, and goals, is a useful place to start.
Cooke Wealth Management works with individuals and families throughout Huntington Beach, Orange County, and Southern California to build personalized financial plans grounded in fiduciary guidance. If you're ready to talk through your goals, scheduling a Discovery Session is a straightforward way to see whether the fit is right.
Frequently Asked Questions
What does "tailored" wealth management actually mean?
Tailored wealth management means building a financial plan around your specific income, goals, risk tolerance, and circumstances rather than applying a generic template. It also means revisiting the plan regularly as your life changes, since a strategy that fit years ago may no longer be appropriate.
How can two families with the same amount invested need completely different strategies?
Two portfolios of the same size can require very different strategies depending on when the money will be needed and what the assets are meant to accomplish. A 35-year-old with decades until retirement typically has more capacity for risk than a 65-year-old already drawing income. This is why portfolio size alone doesn't determine the right strategy.
How does Huntington Beach's cost of living affect retirement planning?
Huntington Beach's housing costs and overall cost of living are higher than national averages, which changes how much is genuinely "enough" for a comparable retirement lifestyle. A generic retirement calculator based on national figures can significantly understate local needs.
What is concentration risk, and why does it matter for Huntington Beach homeowners?
Concentration risk is the risk of amplified losses from having too much wealth tied to a single investment, property, or employer. Many Huntington Beach homeowners have a significant share of net worth tied to their home, and some professionals carry concentrated equity compensation as well. A tailored plan evaluates this concentration and builds the rest of the strategy accordingly.
How often should a tailored financial plan be updated?
Most advisors recommend at least an annual review, with additional check-ins after major life events like a job change, inheritance, or approaching retirement. A plan that isn't revisited regularly can gradually stop reflecting your actual circumstances, even if it was genuinely tailored when first created.
Is a fiduciary advisor automatically free of conflicts of interest?
No. Fiduciary duty requires an advisor to identify and either eliminate or fully disclose conflicts of interest, not to have none at all. Understanding how conflicts are disclosed and managed matters more than assuming a fiduciary label means conflict-free advice.
How do I get started with Cooke Wealth Management?
Cooke Wealth Management offers a free Discovery Session to discuss your financial goals and determine whether the firm's tailored approach fits your needs. From there, the firm builds a personalized plan rather than applying a generic template. You can schedule that initial conversation directly through the firm's contact page.